What Is Collateral Management in Commercial Lending?
Collateral management is how lenders track, value and protect the assets securing their loans. Learn the process, key elements, monitoring rules and common pitfalls.
What is collateral management? Collateral management is the ongoing process of identifying, valuing, documenting, insuring, monitoring and legally protecting the assets pledged to secure a loan, from origination until the loan is repaid. It helps banks, credit unions and commercial lenders make sure collateral stays properly documented, adequately valued and enforceable. For example, a $1 million loan secured by $1.5 million of equipment needs regular checks on the equipment’s value, insurance and lien status for the life of the loan.
A regional commercial lender discovered the problem during a CRE workout on a mixed-use property that had gone nonperforming. The UCC-1 financing statement filed against the borrower’s equipment at origination had lapsed eighteen months earlier. Nobody had scheduled the five-year continuation filing. A junior creditor that had filed its own continuation had kept its perfection. The senior lender’s priority position, which the loan file clearly showed as secured, was no longer enforceable, and the recovery analysis changed in a single conversation with outside counsel.
Nobody had done anything wrong at origination. The lien was filed correctly, the documentation was complete, and the credit was underwritten with care. The problem was that collateral management had been treated as a documentation task rather than a continuous monitoring discipline, and the five-year statutory clock ran out while the institution was watching something else.
Key Takeaways About Collateral Management
Collateral management is a core part of lending strategy, affecting credit risk, capital efficiency and how much a lender actually recovers if a loan defaults.
Most failures happen after closing, not at origination: stale valuations, lapsed liens, missed insurance renewals and LTV drift.
Different collateral types need different monitoring. Real estate, equipment, inventory, receivables and agricultural assets change value at different speeds.
Regulators expect it. Since 2023, interagency CRE guidance has required written policies on when collateral valuations must be updated.
Stakes are rising in 2026: $875 billion of commercial real estate mortgages mature this year, and rates rose again in September.
Technology helps by centralizing collateral data, automating deadline tracking and surfacing exceptions across the whole portfolio.
What Collateral Management?
Collateral management is the ongoing process of tracking, monitoring, valuing, and maintaining the legal enforceability of the assets that secure a commercial loan portfolio. Starting from the day a loan funds through its repayment or resolution. It is a different and more demanding function than collateral capture at origination, which is where most institutions concentrate their effort and attention.Collateral is identified, appraised, and perfected at origination. Then the lien is filed, the flood certification is obtained, the title policy is issued, and the asset is documented in the loan file. That process is well understood and generally well executed. What happens afterward is where the discipline of collateral management begins and where most institutions’ systematic attention ends.
The lifecycle of collateral after funding has several distinct phases. Valuations need to be updated as market conditions shift, because the appraisal completed at origination reflects conditions that may no longer exist. Lien documentation must be maintained for currency: under Article 9 of the Uniform Commercial Code UCC-1 financing statements lapse after five years unless a continuation statement is filed within the six-month window before that anniversary. Flood certifications expire. Title issues that were noted and deferred at closing can become consequential during a workout. LTV ratios need to be recalculated as the loan amortizes and collateral values move, because the coverage that existed at funding may have drifted significantly in either direction. Across all of this, exceptions need to be tracked, resolved, and documented in a form that satisfies examiner scrutiny.
Effective collateral management solution helps lenders maintain accurate visibility into the assets securing their loans. By tracking collateral values, ownership, insurance, documentation, and required reviews, banks and credit unions can identify risks earlier, support compliance, and make more informed lending decisions. A centralized collateral management process also reduces manual work and helps lenders manage growing commercial loan portfolios more efficiently. Ultimately, strong collateral management helps protect the lender while creating a more organized and transparent lending process.
Treating this as an origination function that continues passively into the life of the loan is the fundamental misunderstanding that produces most collateral management failures.
What Is Collateral Management in Banking?
In banking, collateral management usually sits with credit administration or loan operations. These teams keep collateral records current, order reappraisals, track insurance and UCC deadlines, manage exceptions, and report collateral coverage to credit officers, the board and examiners. In larger banks, a dedicated collateral management unit may handle these tasks across the commercial portfolio, supported by collateral management software.
Collateral Management in Lending vs. Capital Markets
The term “collateral management” also has a second meaning. In investment banking, treasury and structured finance, it refers to managing the cash and securities posted as margin for derivatives, repo and securities lending trades, often daily and through custodian banks or a collateral agent. In structured finance, such as collateralized loan obligations (CLOs), a collateral manager selects and monitors the pool of loans backing the securities. This guide covers collateral management in commercial lending: the real estate, equipment, inventory, receivables and other business assets that secure loans to businesses.
The Collateral Management Process, Step by Step
The collateral management process follows the loan from approval to payoff:
Identify and document the collateral. Record each pledged asset, link it to the right borrower and loan, and confirm ownership.
Value it. Order an appraisal or evaluation for real estate, and use market data, inspections or borrowing base reports for equipment, inventory and receivables. This commercial collateral evaluation sets the starting loan-to-value ratio.
Perfect the lender’s interest. File the UCC-1 or record the mortgage, obtain title insurance and the flood determination, and confirm lien priority.
Require insurance. Confirm the borrower has adequate property, casualty and, where required, flood insurance, with the lender named as loss payee or mortgagee.
Monitor throughout the loan. Track valuations, LTV, borrowing base certificates, insurance renewals, inspections and UCC continuation deadlines.
Manage exceptions. Flag and resolve missing documents, expired insurance, stale appraisals and coverage shortfalls, with an owner and deadline for each.
Report. Give credit officers, the board and examiners a clear view of collateral coverage and exceptions across the portfolio.
Release or enforce. Release liens when the loan is repaid, or protect and liquidate the collateral if the borrower defaults.
Key Elements of Collateral Management
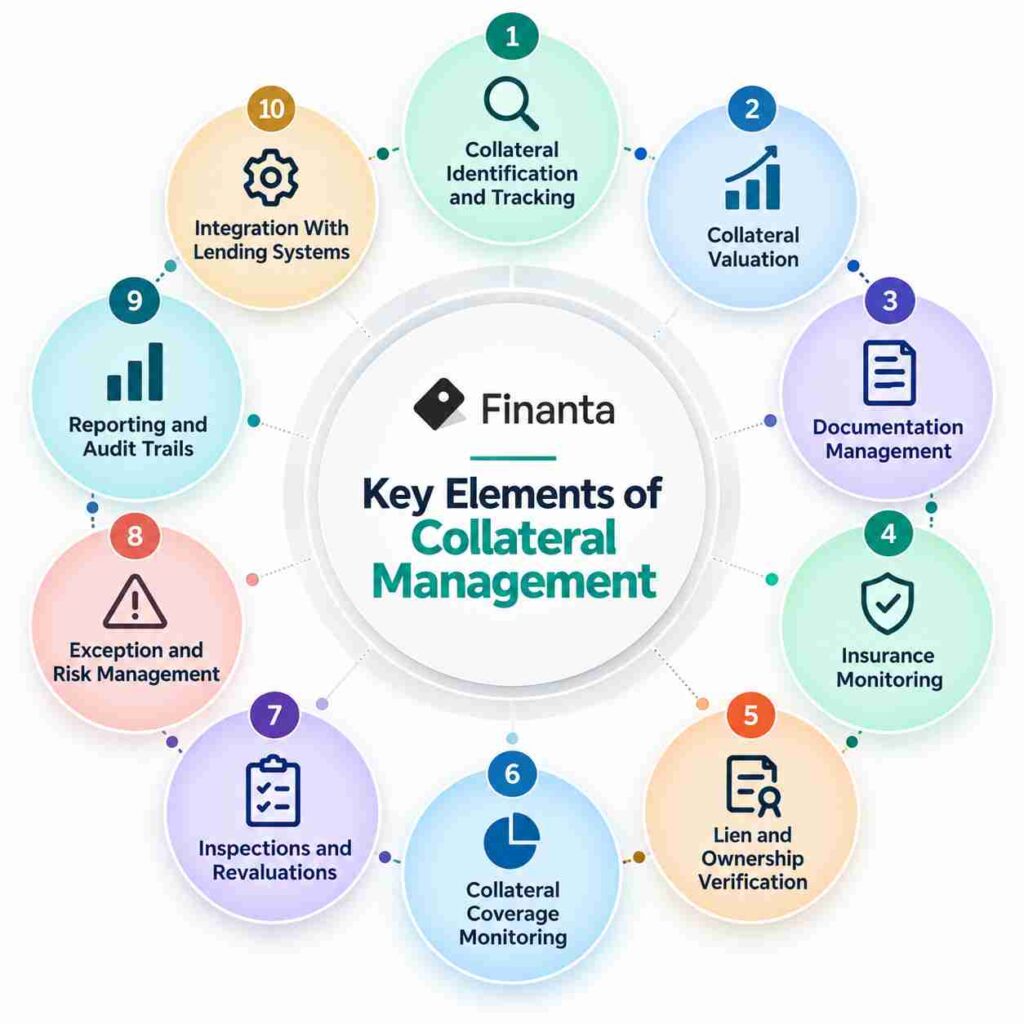
The effective key elements of collateral management are identification, valuation, documentation, insurance, lien monitoring, coverage tracking, inspections, exception management, reporting, and system integration. Together, these processes help lenders manage collateral throughout the commercial loan lifecycle, reduce operational risk, and make better-informed commercial lending decisions.
Collateral identification and tracking: accurate records of every asset securing a loan, linked to the right borrower and facility.
Collateral valuation: regular appraisals, evaluations, market values or inspections, depending on the asset type, to confirm coverage.
Documentation management: appraisals, title documents, insurance certificates, UCC filings, inspection reports and legal agreements stored where teams can find them.
Insurance monitoring: tracking coverage, expiration dates and renewals so gaps are caught early.
Lien and ownership verification: monitoring liens, titles, ownership records and UCC filings to confirm the lender’s legal interest.
Collateral coverage monitoring: recalculating loan-to-value (LTV) and coverage ratios as balances and values change.
Inspections and revaluations: periodic site visits, field exams and updated valuations for assets whose condition or value can change.
Exception and risk management: flagging expired insurance, missing documents, outdated valuations, insufficient coverage and overdue inspections before they become bigger problems.
Reporting and audit trails: portfolio-level collateral reports and a history of what is pledged, its value and the actions taken.
Collateral Types in Commercial Lending, and Why Their Diversity Is the Problem
Commercial lending collateral is not uniform, and the challenge is not just volume. Different collateral types lose value at different speeds, need different revaluation schedules and use different lien perfection methods. Applying one generic monitoring process to all of them means using logic designed for one asset class on assets that behave nothing like it.
Collateral type
How value changes
Typical monitoring
Commercial real estate
With rates, occupancy and local markets
Reappraisal or evaluation per policy and market events; insurance and flood tracking
Equipment
Depreciates, often faster than the loan amortizes
Periodic revaluation against secondary-market benchmarks; UCC continuations
Inventory and receivables
Changes daily with the business
Borrowing base certificates, field exams, aging and concentration checks
Agricultural collateral
Moves with commodity prices and weather
Seasonal reviews of crops, livestock and land values
Cash and securities
Moves with markets
Control agreements and market-value checks
Commercial real estate is the largest collateral category by value in most commercial portfolios. CRE values move with interest rates, occupancy and local economic conditions, and can drift far from origination appraisals over three to five years. Office and non-owner-occupied properties have seen material value declines since 2022. OCC commercial credit guidance expects banks to run appraisal and evaluation programs that keep pace with market conditions rather than relying on origination-era values. See our guide to CRE collateral management.
Equipment depreciates on asset-specific curves that often run faster than the loan amortizes, especially in technology-heavy industries. A machine worth 80 cents on the dollar at origination may be worth 40 cents two years later, while the loan balance has fallen only slightly. A lender that isn’t tracking equipment against current secondary-market values is carrying LTV exposure it hasn’t measured.
Agricultural collateral behaves differently again. Commodity price cycles, weather and seasonal cash flows can move the value of standing crops or livestock within a single growing season, in ways no annual review can capture.
Inventory and accounts receivable are the most labor-intensive to monitor because they change continuously with business performance. A revolving line secured by receivables needs ongoing borrowing base monitoring, periodic field exams to verify the quality and aging of receivables, and attention to customer concentration. A lender that files the security agreement and reviews the facility once a year isn’t managing this collateral; it’s only documenting it.
What Collateral Monitoring Do Lenders Require?
Most commercial lenders require borrowers and their own teams to keep collateral current in five areas:
Valuations: periodic reappraisals or evaluations, plus updates when market conditions or the borrower’s finances change.
Financial and borrowing base reporting: monthly or quarterly borrowing base certificates for receivables and inventory lines, and annual financial statements.
Insurance: proof of continuous property, casualty and flood coverage, with the lender named as loss payee or mortgagee.
Lien and title status: UCC continuations before the five-year lapse, and updated title or flood determinations when a loan is increased, extended or renewed.
Physical condition: site inspections for real estate and equipment, and field exams for asset-based loans.
How Monitored Disbursements Protect the Lender’s Collateral Position
On construction and improvement loans, lenders release funds in stages, called draws, only after confirming the work has been done. Before each draw, an inspector verifies progress, the lender checks that invoices and lien waivers from contractors are in place, and title is updated to make sure no new liens have been filed. This keeps the loan balance in line with the value actually added to the property, and protects the lender’s first-lien position from mechanics’ liens.
Tracking Specialty Collateral: Many commercial portfolios also include specialty collateral, such as aircraft, vessels, rolling stock, intellectual property, liquor licenses or crops. These assets often use different registries and perfection rules than standard UCC filings, and need their own valuation sources and review schedules. A collateral system should let lenders define these asset types with their own fields, documents and deadlines, rather than forcing them into a generic record.
Mapping the Assets Actually Pledged Under a Credit Agreement: A credit agreement may pledge “all assets” while specific schedules exclude certain items, and later amendments may add or release collateral. Lenders should keep a collateral schedule for each facility that maps every pledged asset to the relevant agreement, lien filing and valuation, and update it with each amendment. This makes it clear what the lender can actually claim in a default.
What Happens During Collateral Due Diligence?: Before a loan closes, or before a portfolio is bought or sold, collateral due diligence confirms that the collateral exists, is owned by the borrower, is valued correctly, is properly insured and is legally perfected. It typically includes appraisal review, title and lien searches, insurance verification, environmental reports for real estate, and a review of exceptions. Lenders selling a portfolio often have their collateral insurance program audited first, so the buyer can confirm every asset is covered.
Why Is Collateral Management Important?
Collateral management protects the lender’s recovery position, keeps credit decisions grounded in current data, and shows examiners that collateral controls actually work. Without it, lenders face outdated valuations, missing documents, expired insurance and unexpected exposure.
Reduces lending risk. Lenders know what is pledged, what it is worth and whether coverage is still adequate, and can spot problems before a loan becomes distressed.
Keeps collateral information accurate. Property values move, equipment depreciates, insurance expires and lien details change. Centralized records stop teams relying on outdated data.
Supports better loan decisions. Current LTV and coverage figures speed up renewals, limit increases and exposure reviews.
Helps maintain compliance. A structured process creates an audit trail showing that appraisal, insurance, lien and inspection requirements are being met.
Prevents missed renewals and expirations. Alerts for insurance, appraisal, inspection and UCC deadlines catch them before they become exceptions.
Improves operational efficiency. Teams stop searching spreadsheets, emails and shared folders for collateral information.
Provides portfolio visibility. Lenders can see across the book which loans have stale valuations, insufficient coverage, expiring insurance, missing documents or concentration risk.
Strengthens borrower relationships. With accurate data on hand, lenders answer borrower requests faster and ask for fewer documents at renewals and amendments.
Why the Stakes Around Collateral Management Are Higher Right Now
Several forces have raised the cost of collateral management gaps.
A wave of maturing CRE loans. About $875 billion of commercial and multifamily mortgages, 17% of the $5.0 trillion outstanding, mature in 2026, with banks holding $396 billion of them, according to the Mortgage Bankers Association. Many were underwritten in 2020–2022 on appraisals that no longer reflect today’s values. Every maturity is a moment when stale collateral data turns into a real decision.
Rising rates and pockets of credit stress. The Federal Reserve raised its target range to 3.75%–4.00% in September 2026, its first increase since 2023, which puts pressure on property values and borrower cash flow. FDIC data show the noncurrent rate on construction and development loans reached 0.99% in Q2 2026, above the rate for all loans for the first time since 2014 (analysis of FDIC data).
Explicit regulatory expectations. The 2023 interagency Policy Statement on Prudent Commercial Real Estate Loan Accommodations and Workouts (Federal Reserve SR 23-5), issued with the OCC, FDIC and NCUA, expects institutions to have written policies on when collateral valuations must be updated, including when market conditions change or a borrower’s finances deteriorate. Examiners review these policies and whether they are followed.
Growing portfolios, same processes. Many institutions built their collateral tracking for books of a few hundred loans and now manage far more with the same spreadsheets and staff. Revaluation schedules, UCC deadlines and exception workflows don’t scale on their own. For the portfolio-level view, see collateral risk management.
What Is a Collateral Loan?
A collateral loan is a secured loan in which the borrower pledges an asset to the lender as security. Common collateral includes real estate, vehicles, equipment, inventory, accounts receivable and securities. Before approving the loan, the lender evaluates the asset’s value, ownership, condition and legal status. If the borrower defaults, the lender may take possession of and sell the asset, subject to the loan agreement and applicable law, to recover the debt. That is why the collateral must be managed for the whole life of the loan.
Where Most Lenders Fall Short
The root failure is the same across institution types and sizes: collateral management is treated as a documentation discipline rather than a monitoring discipline. The collateral file is assembled carefully at origination, filed correctly, and then left to the periodic review cycle to catch whatever has changed. That worked when books were smaller and markets calmer. It doesn’t today. It shows up in four ways.
Stale valuations. Appraisals that haven’t been updated since closing leave the lender carrying loans against values that may no longer exist. This is most acute in CRE, but it applies to equipment depreciating faster than the loan amortizes, inventory losing value with the borrower’s business, and farmland moving with commodity cycles. A lender that discovers a stale valuation in a workout has lost its options; one that catches it through monitoring keeps them.
Lien perfection gaps. Under UCC Article 9, a financing statement lapses after five years unless a continuation is filed in the six months before the fifth anniversary. There is no grace period: a lapsed filing means the security interest is no longer perfected against other creditors, and a junior creditor that kept its filings current can take priority. Flood determinations and insurance need refreshing too, and title issues deferred at closing can become coverage gaps in a workout.
LTV drift. The LTV calculated at origination is a point-in-time number. As the loan amortizes, the balance changes; as markets move, the collateral value changes. A lender that doesn’t recalculate LTV regularly is carrying credit risk it can’t see or price, and will find out at the next review or, more expensively, at default.
Exception accumulation. A missing insurance certificate or an overdue appraisal is manageable on its own. The same exceptions across twenty or thirty loans are a portfolio risk pattern. Lenders that track exceptions in separate spreadsheets or loan files miss the early warning that exception management is supposed to provide.
How to Avoid the Most Common Collateral Management Pitfalls
Most collateral management failures aren’t caused by poor underwriting. They’re caused by processes built for a smaller, simpler book that were never updated. Four disciplines prevent most of them.
Treat lien currency as a live obligation. Track UCC continuation deadlines, flood requirements and title follow-ups in a system that triggers action before the window closes.
Revalue by condition and market events, not just the calendar. A two-year-old appraisal may be fine in a stable market and badly outdated in an office segment under pressure.
Aggregate exceptions at the portfolio level. One exception is a task; ten of the same type across the book is a process failure that needs a different response.
Separate monitoring from origination. Collateral management that lives inside the origination workflow ends at closing. Give it its own process, owners and technology for the life of the loan.
What Collateral Management Looks Like When It’s Working
An institution with working collateral management looks different in every way that matters to a credit officer preparing for an exam or a board meeting. Every collateral record carries a current valuation. Every UCC filing has a tracked continuation deadline with a workflow that starts well before the six-month window closes. Every insurance and flood requirement has a date in the system, not a folder in a cabinet. Every LTV reflects the current balance against a current value, so whether a loan is inside policy is answered by running a report, not building a spreadsheet.
This is what Finanta’s collateral management software is built to sustain. The Collateral 360 view keeps a complete record for every loan, including collateral allocation, current LTV, remaining equity and full documentation history, in one place. The platform integrates with flood certification providers such as CoreLogic, ServiceLink and National Flood Data, and with lien filing services such as Wolters Kluwer, First Corporate and CSC, so documentation deadlines are tracked automatically instead of through calendar reminders. Exception tracking routes each issue to the right person with a deadline and escalation, so exceptions get resolved rather than piling up.
Conclusion
Collateral management in commercial lending isn’t a paperwork function. It’s a continuous risk discipline that decides the lender’s real recovery position on every secured loan. With CRE maturities peaking, rates rising and portfolios growing, the cost of gaps between how most institutions manage collateral and what sound practice requires is going up.
Origination gets the collateral relationship right. What happens over the next five or ten years, across market cycles, rate moves, borrower changes and new regulatory expectations, is where the discipline holds or breaks down. The next step is understanding how individual collateral gaps add up to portfolio-level risk, which we cover in collateral risk management.
What does lien perfection mean in commercial lending and what are the most common perfection failures?
Perfection establishes a creditor’s enforceable priority over collateral against other creditors and in bankruptcy. Common failures include lapsed UCC-1 financing statements, expired flood certifications, and unresolved real property title issues. These gaps can weaken a secured creditor’s recovery position and create significant risks during foreclosure, bankruptcy, or other enforcement proceedings, even when the loan was properly documented at origination.
How frequently should LTV ratios be recalculated across different collateral types?
Collateral recalculation frequency should reflect collateral type and market conditions. Commercial real estate typically requires annual reappraisal, with interim reviews during market stress or borrower deterioration. Equipment should be revalued periodically against secondary-market benchmarks. Inventory and receivables require ongoing borrowing-base monitoring and field audits. Covenant breaches, missed payments, borrower deterioration, or significant industry changes should trigger an off-cycle LTV review.
What is the difference between a collateral exception and a collateral deficiency, and why does the distinction matter for exam preparation?
A collateral exception is a documented policy deviation actively tracked toward resolution, while a collateral deficiency represents an actual coverage, documentation, or legal risk. Examiners view documented exceptions more favorably when assigned, monitored, and supported by resolution plans. Undiscovered or unmanaged deficiencies may indicate credit administration failures, especially when collateral enforceability or coverage is compromised.
How does collateral risk at the individual loan level become a portfolio-level problem?
Individual collateral gaps are manageable, but risks increase when deficiencies accumulate across a portfolio. Manual, periodic reviews often allow issues such as lapsed UCC filings, stale appraisals, and policy breaches to persist unnoticed. Continuous collateral monitoring helps lenders identify and resolve issues proactively, maintain portfolio-wide visibility, reduce systemic risk, and strengthen credit administration before problems escalate or attract examiner scrutiny.
Why is collateral management important?
Collateral management is important because it helps lenders protect loan assets, maintain accurate collateral values, reduce risk, and ensure compliance throughout the loan lifecycle. By continuously tracking property, equipment, inventory, and other pledged assets, lenders can identify valuation changes, missing documentation, insurance gaps, or lien issues early. Effective collateral management also improves operational efficiency by reducing manual tracking and giving lenders a centralized view of collateral coverage. For commercial lenders, this can support faster decisions, stronger risk controls, and more consistent portfolio management.
What Is Collateral in Finance?
Collateral in finance is an asset that a borrower pledges to a lender as security for a loan. If the borrower fails to repay the loan according to the agreement, the lender may have the legal right to seize or liquidate the collateral to recover the outstanding debt. Common examples include real estate, equipment, inventory, vehicles, securities, and accounts receivable. Collateral reduces lender risk and can help businesses obtain financing by providing security for the loan.
What Can Be Used as Collateral for a Loan?
Collateral for a loan can include valuable assets that a lender can legally secure and reasonably value. Common examples include real estate, commercial property, equipment, machinery, vehicles, inventory, accounts receivable, cash or deposits, securities, and other business assets. The type of collateral accepted depends on the lender, loan type, asset value, liquidity, and applicable lending requirements. Commercial lenders may also use multiple assets together to secure a loan and continuously monitor their value throughout the loan lifecycle.
What Does Collateral Mean?
Collateral means an asset that a borrower pledges to a lender as security for a loan. It gives the lender protection if the borrower fails to repay the loan as agreed. Common examples of collateral include real estate, vehicles, equipment, inventory, securities, and accounts receivable. For example, a business may use commercial property to secure a $500,000 loan. If the borrower defaults, the lender may have legal rights to seize or sell the collateral to recover the outstanding debt.
How does Collateral Management Work?
Collateral management works by identifying, valuing, documenting, monitoring, and maintaining the assets pledged to secure a loan throughout its lifecycle. Lenders typically verify ownership and lien information, assess the collateral’s value, track insurance and documentation, monitor changes in value, and conduct periodic reviews or revaluations. If collateral value falls, documentation expires, or coverage becomes insufficient, the lender can take corrective action. Modern collateral management software can automate these processes, helping lenders maintain accurate collateral records and manage risk more efficiently.